Coverage Options

Here is every route you can take once you are eligible, laid out side by side so you can see what each one asks of you.

Your starting point

What Original Medicare Already Handles

Before you compare anything else, it helps to know what you are handed on day one. Original Medicare comes in two halves, and between them they carry a good share of your care. What they leave behind is the part everyone ends up shopping for.

The Hospital Half

Inpatient stays, a stretch in a skilled nursing facility after a hospital admission, hospice, and some care delivered at home. Most people pay nothing each month for this half because of the taxes already paid across a working life.

The Medical Half

Doctor visits, outpatient procedures, lab work, preventive screenings, and durable medical equipment such as a walker or oxygen. This half carries a monthly premium, a yearly deductible, and a share of every bill that stays with you.

Three ways forward

Where You Go From There

An older couple stretching together in their living room
The bundled route

Medicare Advantage

A private insurer takes over both halves of your Original Medicare and hands you one card to carry. Most of these plans fold in prescription coverage, and many add dental, vision, hearing, or a fitness benefit on top.

The trade is a network. You pay a set amount at each visit instead of a share of every bill, and there is a ceiling on what you can spend in a year, but you generally need to stay with the doctors that plan has signed.

  • One card, one insurer, one set of rules to learn.
  • A yearly limit on what comes out of your pocket.
  • Extras that Original Medicare never covered.
  • Referrals and network rules that you need to respect.
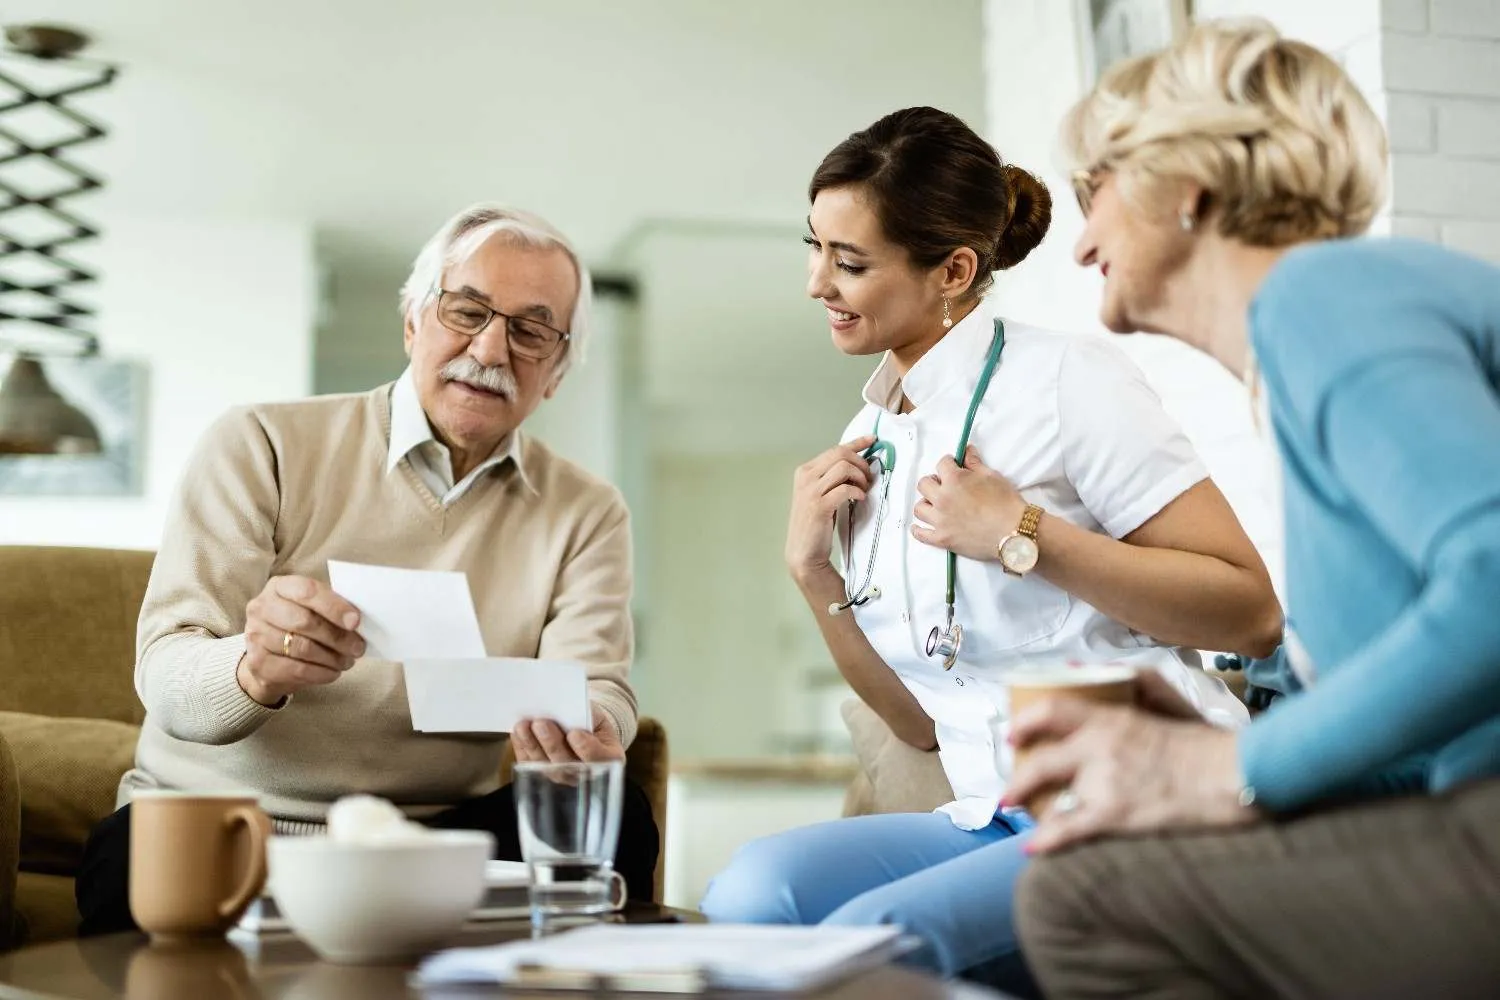
A nurse going over paperwork at home with an older couple
The supplement route

Medicare Supplement Policies

You keep Original Medicare exactly as it is and buy a second policy that steps in behind it. When a bill arrives, Medicare pays its share first and the supplement picks up much of what would otherwise land on your kitchen table.

These policies cost more every month than the bundled route, and prescriptions are bought separately. In return you can walk into almost any office in the country that takes Medicare, with very little left to settle afterward.

  • Any provider who accepts Medicare accepts you.
  • Predictable bills, since most of the leftover share is covered.
  • A separate prescription plan sits alongside it.
  • Health questions can apply if you buy outside your first window.
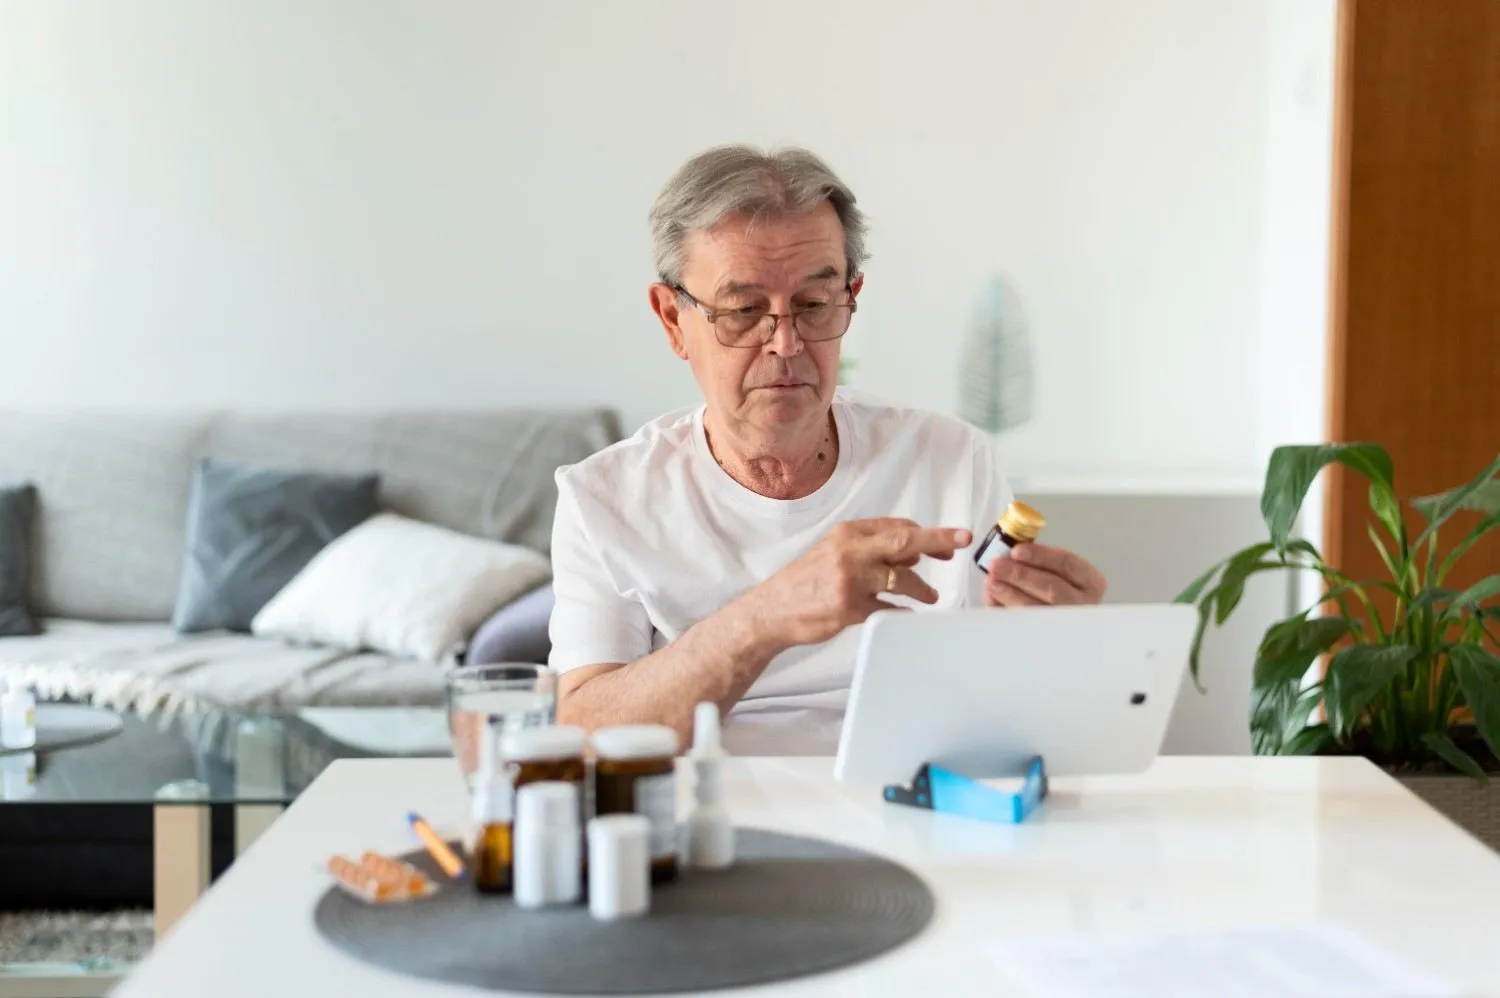
An older man checking a pill bottle against a tablet screen at home
The prescription route

Prescription Drug Plans

Original Medicare leaves nearly every pill you pick up at the counter to you. A standalone drug plan closes that gap, and it is the piece people most often choose on price alone and regret by the middle of the year.

Each plan publishes its own covered list and sorts your medicines into tiers that decide what you pay. Two plans with the same monthly premium can price your exact medicine cabinet very differently, which is why I check yours line by line.

  • Your medicines matched against each covered list.
  • Tier placement checked, not just the monthly premium.
  • Preferred pharmacies compared against where you actually go.
  • A late penalty avoided by signing on at the right moment.
Not sure which fits

Tell Me Who You See and What You Take, and I Will Narrow It Down

There is no route that wins for everyone. The right one falls out of your own list of doctors, medicines, and travel plans once somebody actually reads them.

Get started now
Timing matters

The Windows That Decide When You Can Act

When You First Qualify

Your first window opens shortly before you become eligible and stays open for a stretch afterward. Signing up inside it keeps you clear of the lasting penalty that gets added to a late premium.

The Yearly Review

Once a year in the autumn, everyone gets a chance to switch. Plans change their covered lists and their networks every year, so the plan that suited you last winter may quietly stop suiting you.

When Life Shifts

Moving to a new area, losing coverage from an employer, or a plan leaving your county opens a special window outside the usual dates. Reach out as soon as one of these lands on you.